Logo LG Swiss Broker
Request a consultation

What we do

Services

Complete insurance solutions for individuals and businesses, with a single point of contact and access to over 50 insurers.

Our services

Our services

LG Swiss Broker offers a wide range of specialised services, including risk management, pension advice and business analysis. Our primary aim is to give clients financial peace of mind in the event of unexpected events and the certainty of being adequately protected in every situation, with continuous assistance and a constant presence at their side.

Services for

Individuals

A complete range of insurance services designed to protect every aspect of your business.

Find out more

Services for

Businesses

We offer tailor-made insurance solutions to give you and your family complete peace of mind.

Find out more

The numbers

Discover the peace of mind of having a reliable partner for your insurance.

The financial strength of our company is a tangible result that reflects our constant dedication and commitment.
We work in collaboration with a variety of trusted insurers to offer policies that best meet our clients’ needs. We are also grateful for the recognition of the trade associations, which encourages us to keep working with professionalism and transparency in the insurance sector.

Clients
Contracts
Partners
+
Years of experience
+

Portfolio

Annual premiums in the portfolio

CHF 158.7 million in net annual premiums across 54,488 policies: 41,020 from individuals and 13,468 from businesses.

31%69% 158.7mCHF
  • Individuals31% · 48.9m
  • Legal entities69% · 109.8m

Insurance lines

Breakdown by insurance line

Share of contracts by type of insurance.

33%26%12%12%9% 9lines
  • Property insurance33.3%
  • Motor vehicles26.2%
  • Financial-loss insurance12.5%
  • Private pensions12%
  • Personal insurance9.2%
  • Health insurers4.1%
  • Occupational pensions2.3%
  • Engineering insurance0.5%
  • Mortgage0.1%

Premiums

Annual premium and single premium

Volume of premiums brokered, in millions of francs, for individuals and businesses.

0m50m100m150m200m 109.848.90.0CHF m Annual premiumnet 62.50.0CHF m Single premium
  • Individuals
  • Legal entities

Growth

Client portfolio over the years

From 1995 to today, 32,000 clients: move your cursor over the years.

10k20k30k 1995200020052010201520202026
  • Clients in portfolio
  • New clients per year

For individuals and families

Services for individuals

Household contents

This insurance covers all of your movable personal property located in your home. The insured risks are made up of the four basic risks (fire, natural hazards, water and theft). In addition, supplementary cover can be arranged (comprehensive or all-risks insurance), which allows the cover to be extended comprehensively (for example, insuring a household appliance against incorrect handling). The belongings are insured at your home address and worldwide, with the corresponding cover outside the place of risk.

WOULD YOU LIKE TO FIND OUT MORE?


Private liability

This insurance covers all damage caused to third parties, whether property damage or bodily injury. For example: you step on a friend’s glasses, you spill coffee on a classmate’s computer, you make a woman trip outside the supermarket.

WOULD YOU LIKE TO FIND OUT MORE?


Building + building liability

Building + building liability: The main purpose of building insurance is to insure the building you own against the four basic risks (fire, natural hazards, water and theft). Over time, and as clients’ needs have grown, it is now possible to insure a building against practically any risk; for example: technical cover for solar panels, lift breakdown, garage door malfunction, rodent damage, etc. It is also possible to insure everything that surrounds your home, such as swimming pools, low walls and external infrastructure. Building liability insurance is often taken out together with building insurance and serves to compensate damage caused to third parties; for example: a chipped tile makes a tenant trip, or an unstable roof tile falls on a passer-by.

WOULD YOU LIKE TO FIND OUT MORE?


Valuables

This insurance is called “all risks” precisely because it insures against any risk. It is taken out for items such as jewellery, handbags or paintings. These items are insured against damage, destruction, loss and theft, and are therefore covered all round (360 degrees).

WOULD YOU LIKE TO FIND OUT MORE?


Health insurance

In Switzerland, health insurance is compulsory for all residents. It consists of a part that is compulsory by law (financially the larger of the two) and a supplementary part. This way, you can be certain of having cover for all health problems. In addition, it is possible to extend what the basic insurance offers, for example by adding a private room, and to increase the limits for repatriation, search, rescue, etc.

WOULD YOU LIKE TO FIND OUT MORE?


Pet insurance

As with people, there are now health insurance policies for animals as well. You can take out insurance against possible illnesses or accidents affecting your pet.

WOULD YOU LIKE TO FIND OUT MORE?

Travel

It often happens that you have booked a long-awaited trip but, because of an unforeseen event, are unable to leave. Travel insurance covers the costs of the entire trip (accommodation, transport, etc.) if you are prevented from travelling; for example: due to illness (your own or that of your travel companion), dismissal before the trip or the death of a close relative.

WOULD YOU LIKE TO FIND OUT MORE?


Motor vehicle

Motor vehicle liability insurance is compulsory in order to drive on the road. In addition, you can tailor the ideal cover for your car or motorbike. Besides partial comprehensive cover (glass, theft, hail, martens, etc.) and fully comprehensive cover (damage caused by you), passenger insurance, parking damage, bonus protection, roadside assistance, etc. can be included.

WOULD YOU LIKE TO FIND OUT MORE?


Private legal protection

Legal protection insurance provides cover in the event of legal disputes, whether for advice or for legal costs. It takes on the financial risk of legal cases involving the client, as well as providing advice on matters of tenancy law, employment law, contract law and criminal law. Cover for disputes arising in road traffic can also be included. 

WOULD YOU LIKE TO FIND OUT MORE?


Boats

As with cars, when you buy a boat it is also important to be properly insured. In the same way, you can insure your boat against the basic risks and against possible damage caused by you, such as, for example, a collision with another boat.

WOULD YOU LIKE TO FIND OUT MORE?


Rental deposit guarantees

When a tenancy agreement is signed, a deposit equal to 2 or 3 months’ rent is normally required. If you do not have the necessary liquidity, or do not want to tie it up, a rental deposit guarantee can be taken out. This contract will be given to the landlord in place of the deposit.

WOULD YOU LIKE TO FIND OUT MORE?


Construction guarantees

Once the construction of your building is complete, it is important to have a construction guarantee, so that you are assured that, in the event of insolvency or default by the construction company, any defects in your building will still be remedied.

WOULD YOU LIKE TO FIND OUT MORE?


3rd pillar, disability pensions and lump-sum death benefits

As we know, the Swiss social system is made up of three pillars. The 1st pillar is the AHV/AVS (state pension), which is meant to guarantee you and your loved ones a minimum standard of living in the event of retirement, disability or death. Unfortunately, in most cases this minimum is not enough. The 2nd pillar is the pension fund, which is arranged through your employer and increases the benefits in all three possible scenarios. In theory, the pension fund was designed to maintain your usual standard of living, but here too, in 99% of cases, this is not so. The 3rd pillar was therefore created: with the 3rd pillar you can increase what you will have in retirement by saving more each month; in the same way, you can also insure an additional pension in the event of disability and lump-sum death benefits for your loved ones in the event of death. Like the 1st and 2nd pillars, the 3rd pillar can also be deducted from tax up to a maximum of CHF 7,056 per year.

WOULD YOU LIKE TO FIND OUT MORE?


For the business

Services for businesses

Commerce

This insurance is essentially the same as household contents insurance but, instead of insuring the movable property of a home, it insures a company’s inventory. Here too, you can decide whether to insure only against the basic risks (fire, natural hazards, water and theft) and the related consequential damage, or to extend the cover to include technical damage as well, often by taking out an “all risks” policy.

WOULD YOU LIKE TO FIND OUT MORE?


Building + building liability

Like private individuals, companies also own buildings and can therefore insure themselves against the basic risks or extend their cover, including to possible technical damage or damage to the surrounding environment. As with private individuals, the same applies to WOULD YOU LIKE TO FIND OUT MORE?

Professional and business liability

Much like private liability, companies can also cause damage to third parties. The insurance covers liability under the statutory provisions on civil liability incurred by the insured persons who have unlawfully caused bodily injury (death, injury or other damage to the health of persons), property damage (destruction, damage or loss of things) and, where applicable, pure financial loss, such as incorrect advice.
The insurance covers the civil liability of the following persons: the policyholder, as well as their representatives, other employees and auxiliary staff of the contracting party, in the performance of their activities on behalf of the insured company. The benefits consist of paying the compensation due in the case of justified claims and defending the insured persons against unjustified claims. 

WOULD YOU LIKE TO FIND OUT MORE?


Technical insurance / machinery own-damage (casco)

Fixed or self-propelled machinery can be worth very high amounts for some companies, so it is right to insure it properly. For large machinery and fixed installations there is machinery insurance, which covers any internal damage, including incorrect handling and the resulting financial loss caused by business interruption. For self-propelled machinery, such as an excavator, there is instead machinery own-damage (casco) cover, so that each self-propelled machine can be covered individually against possible overturning or collision damage.

WOULD YOU LIKE TO FIND OUT MORE?


Fleet

This cover is simply an insurance that brings together a number of motor vehicle insurances. For a company with a large fleet of vehicles, it can be very practical and advantageous to insure everything under a single contract. Although there is only one contract, the type of cover required can be tailored for each vehicle.

WOULD YOU LIKE TO FIND OUT MORE?


Business legal protection

Legal protection insurance is an insurance that offers businesses cover in the event of legal disputes, whether for advice or for legal costs. It takes on the financial risk of legal cases involving the company, as well as advice on matters of employment law, contract law and criminal law. This cover applies to disputes with employees, clients or suppliers, as well as to possible disputes arising in road traffic. 

WOULD YOU LIKE TO FIND OUT MORE?


D&O

This cover is a liability insurance for the governing bodies of the company and members of management. If these persons fail to perform their duties and cause damage to the company, this insurance steps in to compensate the damage and, where applicable, to provide legal assistance.

WOULD YOU LIKE TO FIND OUT MORE?


Fidelity (employee dishonesty)

This insurance takes on the financial risk where an employee causes damage resulting from criminal acts, embezzlement, manipulation and falsification of documents. Despite the trust you place in your employees, unfortunately, more often than people think, businesses suffer unlawful acts committed by their own staff. With this insurance, however, you are compensated.

WOULD YOU LIKE TO FIND OUT MORE?


Credit insurance

In short, this insurance takes on the financial risk if your clients do not pay their invoices. As well as being compensated, the insured party does not have to fear liquidity problems.

WOULD YOU LIKE TO FIND OUT MORE?


Group daily sickness allowance

In the case of short-term incapacity for work due to illness, there are two possible solutions in Switzerland: either you take out daily sickness allowance insurance, or you comply with the obligation to continue paying wages laid down in Article 324a of the Swiss Code of Obligations (in Ticino, this means following the Bernese scale). Nowadays almost all employees are insured through daily sickness allowance insurance, partly because most trades provide for it in the collective labour agreement. With this insurance, the employer only has to pay wages during the waiting days, after which the insurance takes over.

WOULD YOU LIKE TO FIND OUT MORE?


Accident insurance (UVG)

Under the Swiss Federal Act on Accident Insurance (UVG) and its ordinances, all employees must be insured on a compulsory basis up to a maximum salary of CHF 148,200. Staff employed for fewer than 8 hours per week are insured only against occupational accidents and occupational diseases, including the direct journey between home and the workplace. Staff employed for 8 hours per week or more are also insured against non-occupational accidents. This insurance pays all costs resulting from an employee’s accident, including medical costs and daily allowances.

WOULD YOU LIKE TO FIND OUT MORE?


UVG supplementary insurance

Although the UVG already provides many benefits, these may sometimes not be enough. The UVG supplementary insurance fills those gaps, for example salaries exceeding the UVG maximum, the waiting period, the missing percentage up to 100% and a private room in the event of hospitalisation. Last but not least, one of the main covers of the UVG supplementary insurance is the waiver of reductions for gross negligence; that is, where the UVG does not pay because of the insured person’s negligence, the UVG supplementary insurance steps in and pays.

WOULD YOU LIKE TO FIND OUT MORE?


Individual daily sickness allowance

Unlike employees, who are insured through the company’s group sickness insurance, a self-employed person can insure themselves individually with an individual sickness policy so as to receive, in the event of illness, a daily allowance for the first two years.

WOULD YOU LIKE TO FIND OUT MORE?


Individual accident insurance

As with individual sickness insurance, there is also individual accident insurance; here too, the insured person secures a daily allowance in the event of an accident for the first two years. Unlike the UVG, treatment costs and the lifelong pension are not included.

WOULD YOU LIKE TO FIND OUT MORE?


Pension fund (BVG/LPP)

In Switzerland, every employee with a salary above CHF 22,050 must be affiliated to a pension fund. The pension fund represents the 2nd pillar and is called occupational pension provision, i.e. the part of provision linked to your occupation. The latter covers all three risks that surround us: 

  • Disability risk
  • Death risk
  • Longevity risk, i.e. retirement

In the event of long-term disability due to illness, you receive a disability pension for yourself and for your children (up to age 18/25). In the event of death due to illness, the surviving spouse/partner receives a widow’s or widower’s pension, as do the children (up to age 18/25). On retirement, you receive what you have saved during your working life.

The type of cover chosen can range from the statutory minimum plan to a plan with maximum credits and pensions as a percentage of salary. Basic plans can be created for employees and executive plans for management staff, depending on needs. In addition, there are also plans known as 1e plans, designed specifically for people with high salaries.

WOULD YOU LIKE TO FIND OUT MORE?


Transport

As the name suggests, this insurance protects against damage occurring during the transport of goods and equipment. Contrary to what people think, very often, especially in trade outside Switzerland and under different legal systems, it is not always clear who is responsible in the event of damage. With this insurance, the problem does not arise.

WOULD YOU LIKE TO FIND OUT MORE?


Cyber

Alongside the many benefits brought by digitalisation, the threats of possible cyber-attacks have also grown: data theft, online fraud, etc. In addition, let us not forget that we are increasingly exposed to damage caused by human error as well. Cyber cover takes on, for example, the following costs:

  • In the event of data loss (caused by malicious software or simply by a spilt cup of coffee), it covers the costs of data recovery, removal of the malicious software or reinstallation of the operating system
  • In the event of misuse or fraud in online payments, it provides assistance in mediation with the credit card companies and covers the remaining financial loss.

WOULD YOU LIKE TO FIND OUT MORE?


WHAT WE OFFER

Our promise?
To always stay by your side!

LG Swiss Broker offers a wide range of specialised services, including risk management, pension advice and business analysis. Our primary aim is to give clients financial peace of mind in the event of unexpected events and the certainty of being adequately protected in every situation, with continuous assistance and a constant presence at their side.

Thanks to in-depth risk analysis, we provide only the right insurance cover, so as to meet every need and requirement. Our role is not limited to simply selling policies; we are committed to providing support throughout the whole process of handling a claim, from reporting to settlement, always acting in the client’s defence to ensure an accurate and fair outcome.
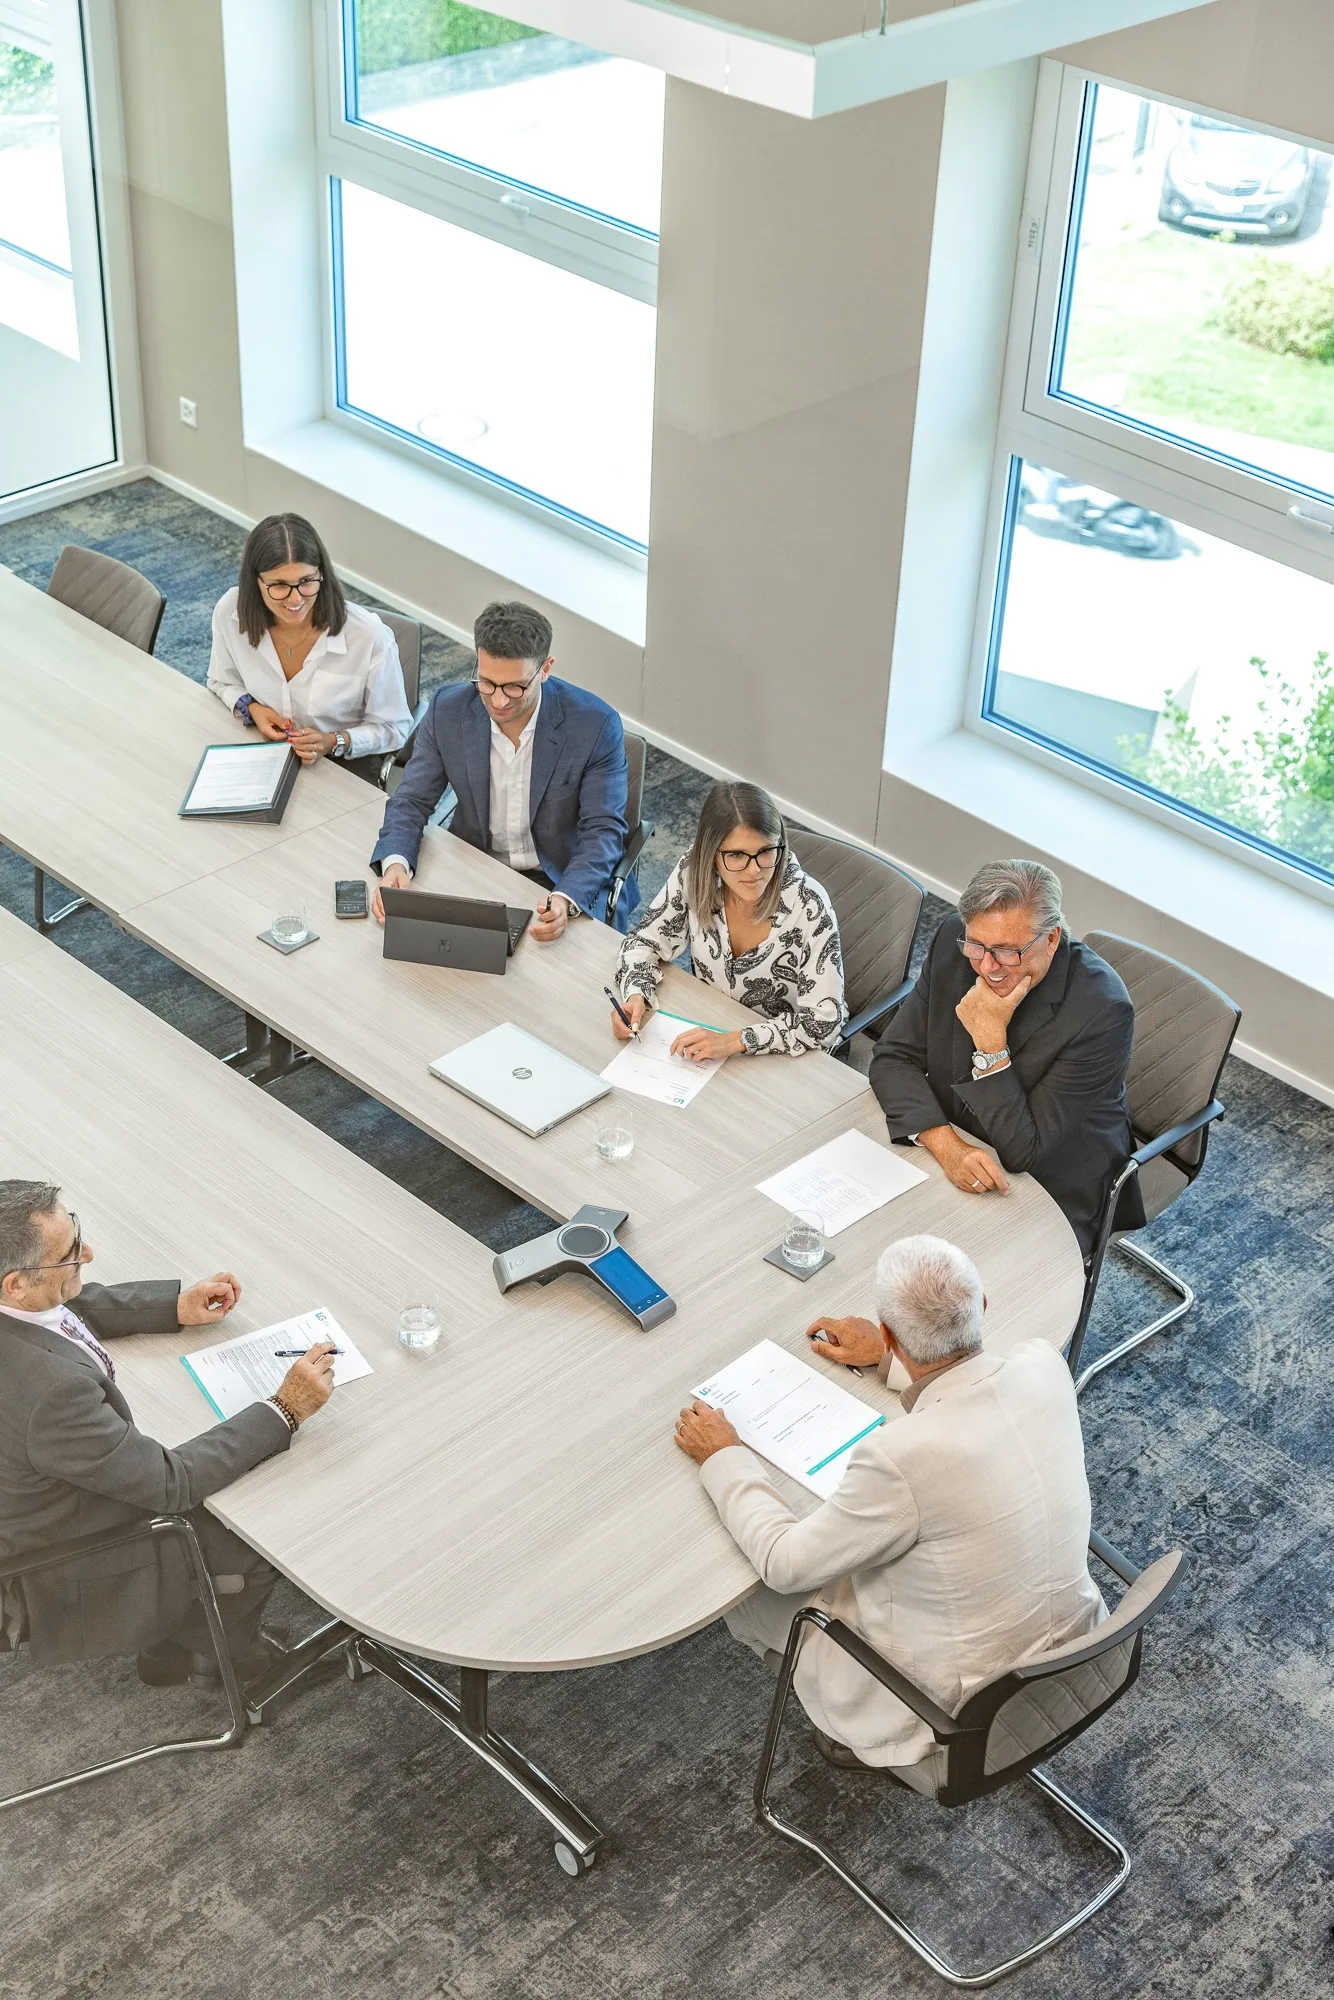
Consulenza assicurativa LG Swiss Broker

We give you access to exclusive market opportunities

At LG Swiss Broker we have access to exclusive market opportunities, which we then pass on to clients at no additional cost. We currently hold a portfolio of more than 230 million Swiss francs and manage more than 20,000 clients every day. With the support of a team of 70 professionals, we work every day to identify and provide the best solution available on the market.

Request a consultation

Frequently asked questions

The answers everyone is looking for

Six of the most common questions before entrusting yourself to a broker. Can’t find yours? Write to us.

Which insurance policies can I entrust to LG Swiss Broker?

All types of cover for individuals and businesses: home and household contents, vehicles, liability, legal protection, accident and illness, pensions (2nd and 3rd pillars), loss of earnings, and business and professional cover.

How does the comparison between insurers work?

After analysing your needs, we request quotes from several of the more than 50 insurers we work with, compare them on cover, exclusions, excess and premium, and present you with a clear recommendation.

How long does it take to receive a proposal?

For standard cover, usually within a few working days; for complex business risks it depends on the insurers involved, but we keep you updated at every step.

Who helps me if I have a claim?

Your adviser: we check the cover, prepare the claim, liaise with the insurer and check the compensation. You can also report a claim online from the dedicated page.

Do you also look after small businesses and the self-employed?

Yes. From the sole trader to the structured SME, we build tailor-made packages: business liability, loss of earnings, occupational pensions, fleets, cyber and sector-specific cover.

Can I cancel a policy before it expires?

As a rule, policies are cancelled at the contractual expiry date with three months’ notice; in some cases (claim, premium increase, change of risk) there are rights of early cancellation. We will review your situation together.

Let’s talk

Contact us

Fill in the form: an adviser will contact you within one working day.

This form is protected by Google reCAPTCHA: Google’s privacy policy and terms of service apply.